Dear taxpayers,
In accordance with Articles 84-89 of the Tax Code of the Republic of Kazakhstan, in cases stipulated by law, the state revenue authorities apply measures to ensure the fulfillment of tax obligations.
, Basic measures:
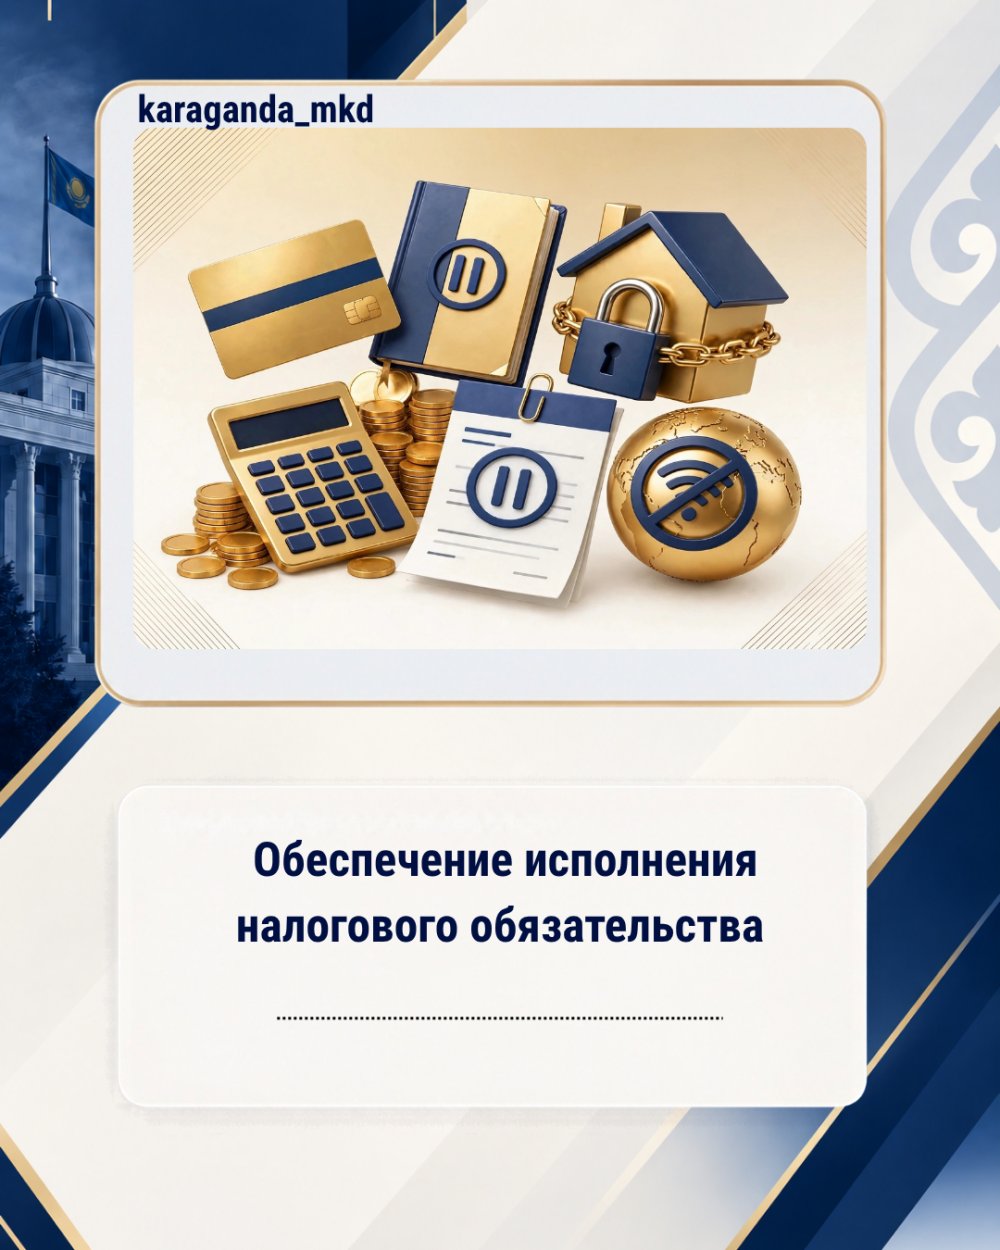
💰 Penalty accrual is made in case of late fulfillment of a tax obligation.
Suspension of expenditure transactions is applied to bank accounts and/or cash desks in the presence of tax arrears exceeding the maximum amount, as well as in other cases established by the Code.
The restriction on the disposal of property is applied in case of tax arrears exceeding the maximum amount, within the amount of the debt, as well as in case of appeal of the notification of the results of the tax audit, within the amount of the contested amount.
Suspension of electronic invoice statements is applied in cases established by Article 88 of the Code, including in case of non-fulfillment of certain notifications and in cases provided for by the Code related to VAT tax reporting.
Restriction of access to Internet resources and (or) an Internet site - is applied to foreign companies operating through an Internet site in Kazakhstan, if the established notifications are not fulfilled.
In order to avoid the application of these measures, we ask taxpayers to fulfill their tax obligations in a timely manner, comply with established deadlines and comply with notifications from state revenue authorities in cases provided for by the Tax Code.
The grounds, procedure for the application, suspension and cancellation of these measures are defined in Articles 84-89 of the Tax Code of the Republic of Kazakhstan.