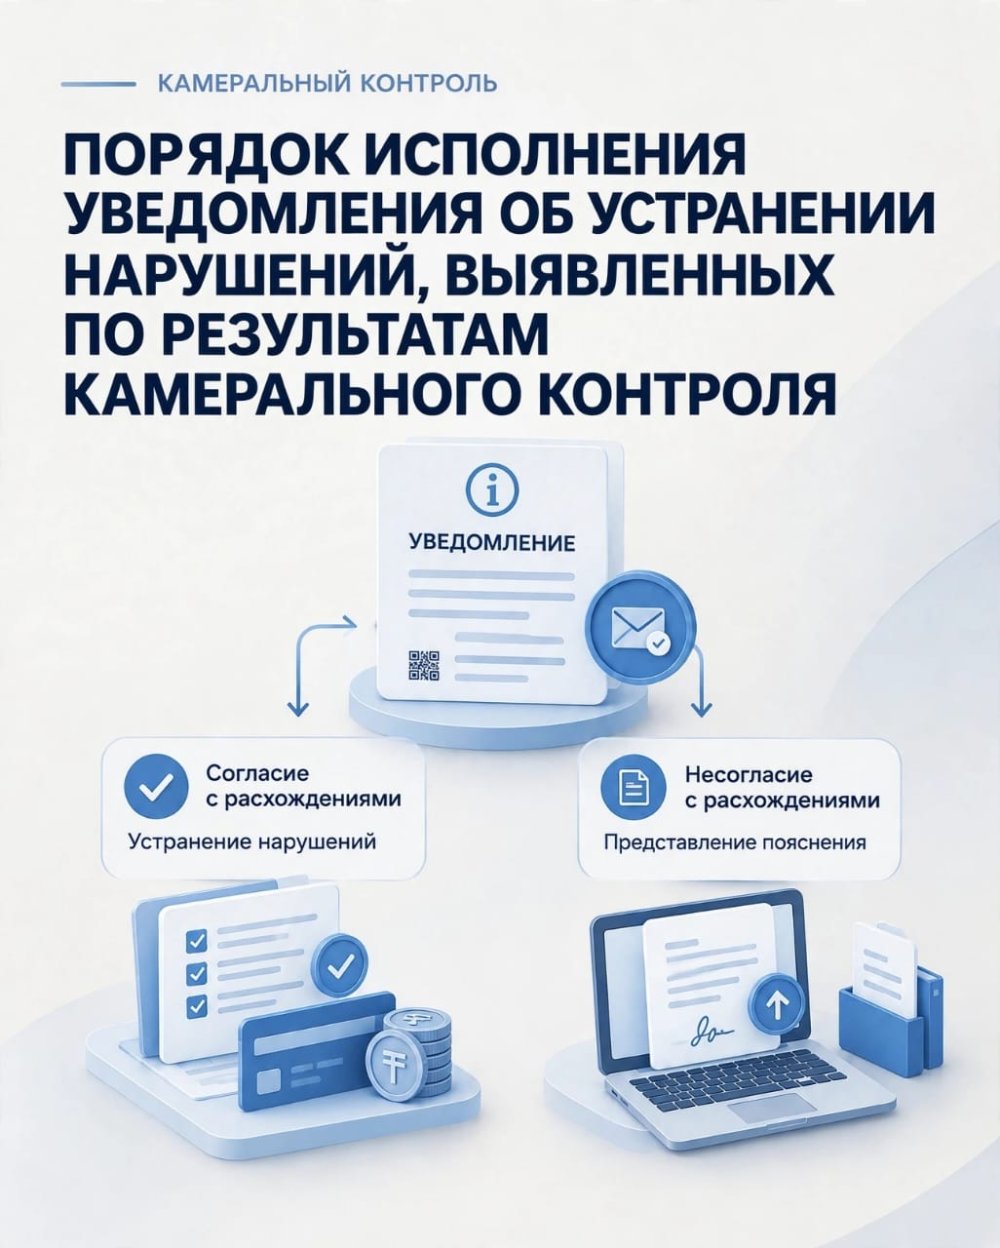
Upon receipt of a notification on the elimination of violations identified by the results of desk control, the taxpayer must eliminate the identified discrepancies or provide an explanation.
If the taxpayer agrees with the identified discrepancies, the notification is executed by eliminating the identified violations, including:
* submitting tax reports for the tax period to which the identified discrepancies relate;
▪️ payment to the budget of the amount of value-added tax previously returned from the budget upon request for VAT refund, as well as penalties for the relevant period;
data reflection in a special mobile application and (or) payment of taxes and social payments — for taxpayers applying a special tax regime for the self-employed;
Performing actions provided for in Article 716 of the Tax Code of the Republic of Kazakhstan in order to switch to the appropriate tax regime.
If the taxpayer does not agree with the identified discrepancies, an explanation of the reasons for the discrepancies is submitted to the tax authority that submitted the notification, which does not entail violations of the tax legislation of the Republic of Kazakhstan, except in cases established by law.
The explanation should contain:
▪️ identification data of the taxpayer and the tax authority;
▪️ Notification number and date;
The reasons for disagreement with the discrepancies indicated in the notification;
▪️ date and signature;
A list of supporting documents, if available.
The tax authorities are prohibited from requesting documents for the execution of the notification.
Explanations are not allowed in cases established by tax legislation, including for individual transactions and transactions related to the unlawful allocation of expenses for deductions in the calculation of corporate income tax and the allocation of VAT as a set-off.
At the same time, this restriction does not apply to transactions (operations) for which the court has established the actual acquisition (receipt) of goods, works, and services by the taxpayer.
The deadline for the execution of the notification may be suspended when filing a complaint with the court to confirm the actual acquisition (receipt) of goods, works, and services in cases provided for by tax legislation.
A copy of the judicial act on the acceptance of the complaint for production is submitted to the tax authority that submitted the notification.
The suspension is valid from the date of the issuance of the said judicial act until the date of its entry into force. #Zamen_tartip_the Law_and_ Order