The Agency of the Republic of Kazakhstan for Regulation and Development of the Financial Market
About the Agency
The Agency of the Republic of Kazakhstan for Regulation and Development of the Financial Market (the Agency) has been operating since 1 January 2020 in accordance with Presidential Decree No. 203 dated 11 November 2019 “On Further Improvement of the Public Administration System of the Republic of Kazakhstan”.
The Agency is a public authority responsible for protection of the rights and legitimate interests of financial consumers, promotion of the stability of the financial system and the development of the financial market, and carrying out regulation and supervision of the financial market and financial institutions, as well as other entities within its competence.
The Agency is the legal successor to the rights and obligations of the National Bank of Kazakhstan (NBK) with respect to the functions and powers transferred to it.
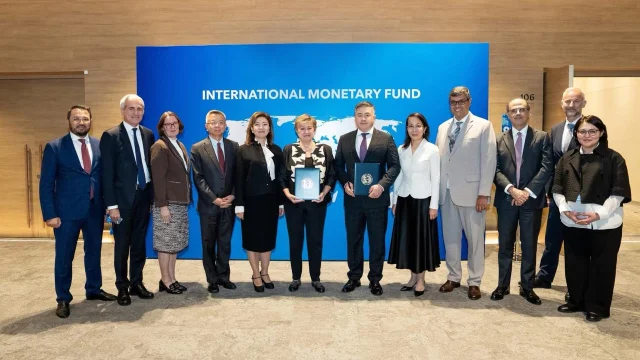
Since 13 October 2026, a delegation of the Agency of the Republic of Kazakhstan for Regulation and Development of the Financial Market, led by Chairperson Madina Abylkassymova, has been participating in the Annual Meetings of the International Monetary Fund (IMF) and the World Bank Group in Bangkok, Thailand. During a meeting with IMF Managing Director Kristalina Georgieva , the parties discussed the current state of Kazakhstan’s financial sector, its development prospects and reform priorities, financial stability, and bilateral cooperation. The Agency Chairperson highlighted the constructive cooperation with the IMF and its technical assistance in drafting the new Law on Banks. Madina Abylkassymova also attended the Caucasus and Central Asia ministers and central bank governors meeting with IMF Deputy Managing Director Bo Li . Discussions focused on the importance of a resilient financial sector for regional integration, enhancements to banking regulation, and the adoption of international best practices in supervision. Particular attention was paid to cooperation with the Caucasus, Central Asia, and Mongolia Regional Capacity Development Center (CCAMTAC), based in Almaty. Meetings with IMF representatives also addressed the implementation of a comprehensive risk-based supervisory framework for the capital market and insurance sector. The parties discussed further expert cooperation in drafting new laws on the capital market and insurance to support reforms in these sectors.
The National Bank of the Republic of Kazakhstan, the Agency of the Republic of Kazakhstan for Regulation and Development of the Financial Market, the Ministry of Finance of the Republic of Kazakhstan, the Astana International Financial Centre (AIFC), and the Asian Development Bank (ADB) announce the publication of the Bond Market Guide for Kazakhstan - the first document of its kind in Kazakhstan’s history. The Guide was prepared under the ASEAN+3 Bond Market Guide initiative - a series of publications by the ASEAN+3 Bond Market Forum (ABMF), whose secretariat functions are provided by ADB. Kazakhstan joined the Forum as an official observer in 2025. The document covers all key aspects of Kazakhstan’s bond market: the history and key milestones of market development; the legal and regulatory framework: securities legislation, listing and disclosure requirements, and non-resident access conditions; types of debt instruments: government and corporate bonds, money market instruments, and Islamic securities (sukuk); trading, clearing, and settlement infrastructure on KASE and AIX, including specifics of the AIFC jurisdiction; the tax regime, participation costs, and access conditions for foreign investors; current challenges, outlook, and priorities for further market development. The Guide is intended for international investors, issuers, financial intermediaries, regulators, and researchers seeking a current and structured overview of Kazakhstan’s capital market. The document is available on the ADB website at: https://www.adb.org/publications/bond-market-guide-kazakhstan . Statements from the Parties National Bank of the Republic of Kazakhstan “The bond market plays a key role in financing the economy and is one of the priority areas of financial market development in Kazakhstan, providing the formation of a market yield curve and effective transmission of monetary policy signals. In this regard, the National Bank of the Republic of Kazakhstan, together with government agencies and market participants, is implementing a comprehensive set of measures to develop infrastructure, improve regulation, enhance liquidity, and broaden the investor base. As part of this work, the Bond Market Guide for Kazakhstan has been prepared jointly with the Asian Development Bank, structuring information about the market in accordance with international standards and aimed at increasing its transparency and investment attractiveness.” Aliya Moldabekova , Deputy Governor, National Bank of the Republic of Kazakhstan Agency of the Republic of Kazakhstan for Regulation and Development of the Financial Market “Regulatory transparency is a fundamental prerequisite for investor confidence. The Guide provides a detailed account of the legal and regulatory framework of Kazakhstan’s securities market and gives foreign participants a reliable reference point when assessing opportunities. The Agency is committed to keeping the document up to date as regulation evolves in line with best international practices. Today, the Agency, together with international advisors, is developing a Securities Market Development Programme through 2030 and a new Capital Market Law - with the goal of modernising a legislative framework that was designed for an earlier stage of market development and no longer reflects the market’s current scale and complexity. The reform aims to bring new issuers and investment instruments to the market, build a sustainable investor base and liquidity, ensure robust protection of all participants’ rights - and ultimately for the capital market to take a more prominent role in financing Kazakhstan’s economy.” Nurzhan Tursunkhanov , Deputy Chairperson, Agency of the Republic of Kazakhstan for Regulation and Development of the Financial Market Ministry of Finance of the Republic of Kazakhstan “A developed and liquid government securities market is the foundation of sound public finances and the ability to attract investment on competitive terms. This Guide provides international investors with objective and structured information on Kazakhstan’s debt instruments. The Ministry of Finance is consistently pursuing a policy of market deepening and broadening the investor base.” Dauren Kengbeil , Vice Minister of Finance, Ministry of Finance of the Republic of Kazakhstan Astana International Financial Centre “The AIFC was established as a world-class financial platform, and bond market development is one of our key priorities. The inclusion of a dedicated chapter on the AIFC’s legal and market infrastructure allows global investors to fully appreciate the advantages of operating through our jurisdiction. We are confident this publication will serve as an effective tool for attracting international capital to the Kazakhstan market.” Renat Bekturov , Governor, Astana International Financial Centre (AIFC) Asian Development Bank “ADB is pleased to support Kazakhstan in preparing this Guide as part of the work of the ASEAN+3 Forum. This publication reflects Kazakhstan’s growing role in regional financial integration and its commitment to attracting international capital in support of economic development. We are confident that the Guide will serve as a valuable resource for investors and market participants considering Kazakhstan as an investment destination.” Utsav Kumar , Country Director, Asian Development Bank (ADB) Kazakhstan Resident Mission Background: About the ASEAN+3 Bond Market Forum (ABMF) The ASEAN+3 Bond Market Forum (ABMF) was established in 2010 under the Asian Bond Markets Initiative (ABMI). The Forum is the leading regional platform for information exchange, policy and regulatory recommendations, and support for bond market integration in the ASEAN+3 region. The ABMF secretariat is provided by the Asian Development Bank. Media Contacts National Bank of the Republic of Kazakhstan: [email protected] Agency for Regulation and Development of the Financial Market: [email protected] Ministry of Finance of the Republic of Kazakhstan: [email protected] , [email protected] AIFC: [email protected] ADB (Media Relations): [email protected]
A meeting was held between the Chairperson of the Agency for Regulation and Development of the Financial Market and a delegation of the International Finance Corporation (IFC) led by Ms. Wiebke Schloemer, IFC Director for Turkey and Central Asia. During the meeting, the Agency and IFC signed a Letter of Agreement for the provision of advisory services. Under this agreement, the IFC will develop recommendations and participate in consultations with public and private stakeholders. The parties also discussed the current results of their bilateral cooperation, including the introduction of ESG standards in Kazakhstan’s financial system, the transformation of microfinance institutions into banks, and IFC support for regulatory and rule-making initiatives.
During Astana Finance Days, the Agency of the Republic of Kazakhstan for Regulation and Development of the Financial Market and the Financial Services Authority of the Sultanate of Oman (FSA) signed a Memorandum of Understanding (MoU). The FSA is responsible for the regulation and supervision of capital markets, the insurance sector, as well as accounting and auditing activities in the Sultanate of Oman. The signing ceremony was attended by the heads of the two financial regulators — Ms. Madina Abylkassymova, Chairperson of the Agency, and Mr. Abdulla Salim Al-Salmi, Executive President of the FSA. The document reflects the parties’ commitment to strengthening cooperation between Kazakhstan and Oman. The Memorandum provides for cooperation in financial technologies, innovative projects, financial education, and the promotion of financial inclusion, as well as the development of joint initiatives aimed at enhancing financial market infrastructure through the use of modern technologies. Particular attention is given to the support and development of the Tabadul platform, which helps strengthen cooperation between regional exchanges and facilitate cross-border trading.
During Astana Finance Days, a meeting was held between a delegation of the Agency of the Republic of Kazakhstan for Regulation and Development of the Financial Market, led by Chairperson Madina Abylkassymova, and Mr. Csaba Kandrács, Deputy Governor of the Hungarian National Bank. The parties discussed prospects for expanding cooperation in the banking sector, as well as challenges in financial regulation related to the growing use of digital assets and cryptocurrencies, the introduction of distributed ledger technologies, the increased risk of fraud, and the emergence of regulatory gaps between traditional financial institutions and new market participants. Earlier, during the state visit of the President of the Republic of Kazakhstan, Kassym-Jomart Tokayev, to Hungary, the Agency and the Hungarian National Bank (Magyar Nemzeti Bank) signed a Memorandum of Understanding on cooperation in the banking sector. The signing ceremony took place on 20 November 2024 in the presence of the leaders of the two countries. The Memorandum aims to enhance cross-border banking supervision in line with the standards of the Basel Committee on Banking Supervision and creates new opportunities for closer cooperation between the Agency and the Hungarian National Bank.
An official ceremony marking the opening of BNK Commercial Bank’s office in Almaty took place today. The bank is the first foreign bank in Kazakhstan established through the transformation of a microfinance organization into a bank. The launch follows extensive work by the BNK team, its advisors, and specialists of the Agency for Regulation and Development of the Financial Market. The entry of a foreign bank into the Kazakh market is in line with the instruction of the Head of State, Kassym-Jomart Tokayev, to attract reliable foreign banks to Kazakhstan and enhance competition in the banking sector . This initiative was announced in September 2023 in the President’s Address to the People of Kazakhstan. The opening ceremony was attended by the leadership of BNK Financial Group and representatives of its subsidiaries, including BNK Busan Bank, BNK Kyongnam Bank, and BNK Capital. The group’s total assets amount to approximately USD 114 billion, with equity capital of about USD 8 billion. “This event is of historic importance for Kazakhstan’s banking sector. BNK Commercial Bank is the first foreign bank established in Kazakhstan through the transformation of a microfinance organization into a bank. It is also the first banking license issued in Kazakhstan in the past 15 years, and the first foreign bank to obtain a banking license in Kazakhstan as part of the implementation of the President’s instruction to attract international financial institutions,” said Madina Abylkassymova, Chairperson of the Agency. The bank has identified lending to small and medium-sized enterprises (SMEs) as its main strategic priority in Kazakhstan. Supporting SME financing is a key component of Kazakhstan’s economic policy and an important priority for the development of the country’s financial sector. In the first half of the year, the SME loan portfolio reached USD 26.7 billion, representing an increase of 8 percent. The opening of BNK Commercial Bank also represents an important step toward strengthening trade and economic cooperation between Kazakhstan and the Republic of Korea. The Agency for Regulation and Development of the Financial Market issued BNK Commercial Bank a banking license on 25 June 2025.
Current State of the Insurance Sector as of September 1, 2026
DESCRIPTION The review is presented in the form of tables and figures. as well as explanatory notes. reflecting major changes in indicators of the insurance sector.- Description of assets structure;- Description of liabilities structure;- Description of insurance premiums structure;- Description of insurance payments structure;- Description of reinsurance activity;- Description of compliance with prudential standards by the insurance sector of Kazakhstan;- Efficiency of the insurance sector of Kazakhstan. The current status of individual financial institutions is posted on the Internet resource of the National Bank of the Republic of Kazakhstan
Published:
Statistics
Amount of Voting Shares in Joint-Stock Companies as of October 1, 2026
Published:
Statistics
Current state of the accumulative pension system as of 01.09.2026
Published:
Statistics
Current State of the Insurance Sector as of August 1, 2026
DESCRIPTION The review is presented in the form of tables and figures. as well as explanatory notes. reflecting major changes in indicators of the insurance sector.- Description of assets structure;- Description of liabilities structure;- Description of insurance premiums structure;- Description of insurance payments structure;- Description of reinsurance activity;- Description of compliance with prudential standards by the insurance sector of Kazakhstan;- Efficiency of the insurance sector of Kazakhstan. The current status of individual financial institutions is posted on the Internet resource of the National Bank of the Republic of Kazakhstan
Published:
Statistics
Current state of microfinance organizations of Kazakhstan as of 1 July 2026
DESCRIPTION The review is presented in the form of tables and graphs, as well as a descriptive part that reflects the main changes in the indicators of microfinance organizations in the Republic of Kazakhstan. - Description of the structure of assets of microfinance organizations of the Republic of Kazakhstan - Description of the structure of the loan portfolio of microfinance organizations of the Republic of Kazakhstan - Description of obligations of microfinance organizations of the Republic of Kazakhstan - Description of the implementation of prudential standards by microfinance organizations of the Republic of Kazakhstan. - Efficiency of activities of microfinance organizations of the Republic of Kazakhstan. The main indicators of microfinance organizations are posted on the Internet resource of the National Bank of the Republic of Kazakhstan
Published:
Statistics
Amount of Voting Shares in Joint-Stock Companies as of September 1, 2026